Common Mistakes in UAE Corporate Tax Return Filing
Common Mistakes in UAE Corporate Tax Return Filing
Common mistakes in UAE Corporate Tax Return filing can lead to unnecessary compliance issues for companies. Companies in the UAE must learn about their tax responsibilities and keep correct financial papers. Filing mistakes, even minor ones, could create some issues in tax reviews. Thus, companies are advised to adopt proper practices before filing. Professional tax planning can minimize mistakes and enhance compliance.
Understanding Common Mistakes in UAE Corporate Tax Return Filing
Common Mistakes in Filing Corporate Tax Returns in the UAE are usually triggered by a lack of understanding of corporate tax requirements. Hence, businesses end up having misunderstandings regarding taxable income, deductions, filing obligations, etc. As a result, companies must examine tax rules applicable for the purpose of preparing the returns. They must also keep comprehensive records of the supporting documents for the numbers provided.
Moreover, it is important for management to ensure that the roles of tax compliance are well-defined.
Missing the Corporate Tax Filing Deadline
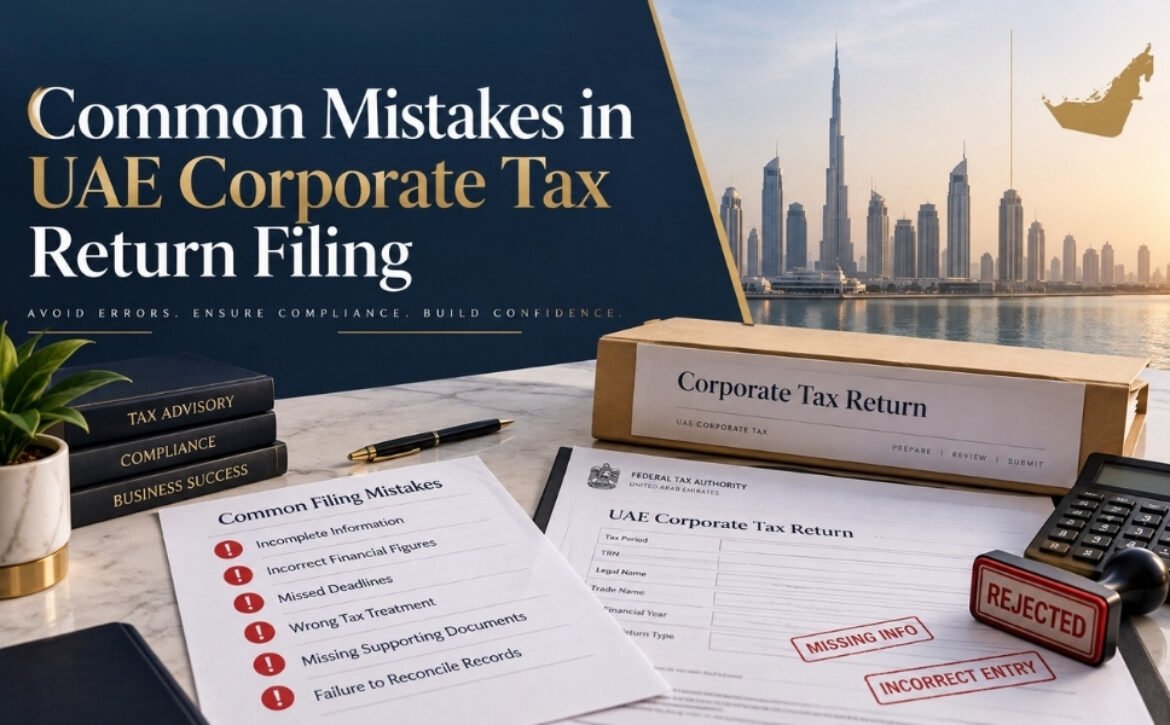
One of the biggest mistakes regarding filing is missing deadlines. Businesses must carefully determine their corresponding filing period early so that they can meet that deadline. Common mistakes in respect of filing corporate tax returns in the UAE include waiting until the last moment to submit documents. This increases the risk of making mistakes during preparation.
This is why businesses should prepare internal compliance calendars to ensure timely preparation and investigation into financial matters.
Reporting Incorrect Financial Information
Proper financial records constitute the basis for corporate tax return filing. Incorrect information about revenue or expenses may create compliance issues. Companies should reconcile their accounting records before they start tax calculations. This means that the information regarding income, expenses, assets, and liabilities must be verified once again. Common mistakes in respect of filing corporate tax returns in the UAE may happen due to the fact that businesses do not have comprehensive accounting records.
Mistakes in Taxable Income Calculation
Accounting profit does not always equal taxable income. There can be variations in corporate taxable income calculation because of certain adjustments. Businesses should be aware of the eligible expenses for tax purposes. It is also important to identify adjustments made to expenses before tax returns are filed. Some common issues during the filing of corporate tax returns in the UAE include inaccurate claims for tax deductions and unverified expenses. Using proper methods of tax calculation will help businesses avoid such issues. It may be useful to consult a professional for complicated transactions.
Poor Record-Keeping
Companies need to have their records in order to ensure their corporate tax return filing. If the documentation is lacking or poorly organized, it can be impossible to verify it in the course of tax audits. Thus, it is essential for companies to have invoices, contracts, financial statements, and other documents in place. Besides, companies need to do the reconciliation of the financial information from time to time. Having spotless record-keeping will ensure the ease of filing tax returns.
Disregarding Related Party Transactions
Businesses must go through related party transactions since they might require special treatment with respect to corporate tax laws. Companies must recognize their presence in the process of accounting. An example of Common Mistakes in UAE Corporate Tax Return Filing is neglecting transactions with connected parties. Businesses should ensure they keep appropriate records in this regard.
Moreover, they need to also study relevant transfer pricing laws in detail. Proper record-keeping will help businesses avoid problems in future audits.
Confusing Free Zone Tax Regulations
Companies operating in Free Zones should not assume that all their income will get favorable tax treatment. Each situation may require different rules. Thus, businesses should examine their activities and revenues. They need to check whether certain conditions are satisfied.
Examples of Common Mistakes in UAE Corporate Tax Return Filing include those due to the misunderstanding of Free Zone tax regulations. Professional consulting can clarify the company’s situation.
Forgetting to Check the Return before Filing
Companies should never file corporate tax returns without checking. Some seemingly small mistakes may lead to disastrous consequences. Hence, firms must ensure the validity of financial information and all papers linked to this information beforehand. Furthermore, management must perform proper checks on crucial tax calculations.
An organized checking procedure can help detect mistakes before filing. As a result, companies may prevent issues connected to compliance.
Not Looking for Professional Tax Advice
Corporate tax issues might be really complicated in case of growing companies. It may be necessary to consider transactions involving numerous entities separately. Using presumptions only may lead to Common Mistakes in UAE Corporate Tax Return Filing. However, hiring professional tax consultants can help to fix problems.
Ways to Enhance Corporate Tax Compliance in Business Sector
Businesses must uphold accurate financial records. Regular financial assessments can help recognize inconsistencies in records before filings begin. Business organizations need to draft specific tax compliance processes and procedures. Employees should be informed about documentation requirements and deadlines for compliance purposes.
It is essential that businesses keep track of updates in relevant regulations. Management benefits from adjusting compliance processes in accordance with evolving requirements.
Every business can encounter problems when it comes to Corporate Tax Return Filing in the UAE. Bad record-keeping practices, inaccurate accounting, missing deadlines. As a result, companies should maintain the accurate financial data necessary for tax preparations.